PayPal Raises Outlook As CEO Battles To Turn Around Payments Giant
 Emma Wheaton
28 Oct 2026

PayPal has lifted its 2026 adjusted earnings forecast as CEO Enrique Lores continues a multiyear turnaround of the payments giant.
The company raised its full-year adjusted earnings guidance to approximately US$5.60 per share, up from US$5.38 previously, after delivering third-quarter earnings that were better than expected.
Third-quarter adjusted earnings reached US$1.45 per share, beating analyst expectations of around US$1.31. Revenue, however, rose 2% year on year to US$8.58 billion, falling short of market forecasts.
Total payment volume increased 6% year on year to US$487.1 billion, or 7% when adjusted for foreign-exchange movements, showing continued activity across PayPal’s payments network.
Despite the improved earnings outlook, profitability remains mixed. Transaction-margin dollars rose 2% to US$3.95 billion, while net income under generally accepted accounting principles (GAAP) fell 14% to US$1.07 billion from US$1.25 billion a year earlier.
Lores has described the turnaround as a multiyear effort that focuses on execution, operational discipline and sustainable, profitable growth.
A key component of the strategy is expanding consumer financial services, including debit cards, credit products and other money-management services, with Venmo emerging as an important growth driver.
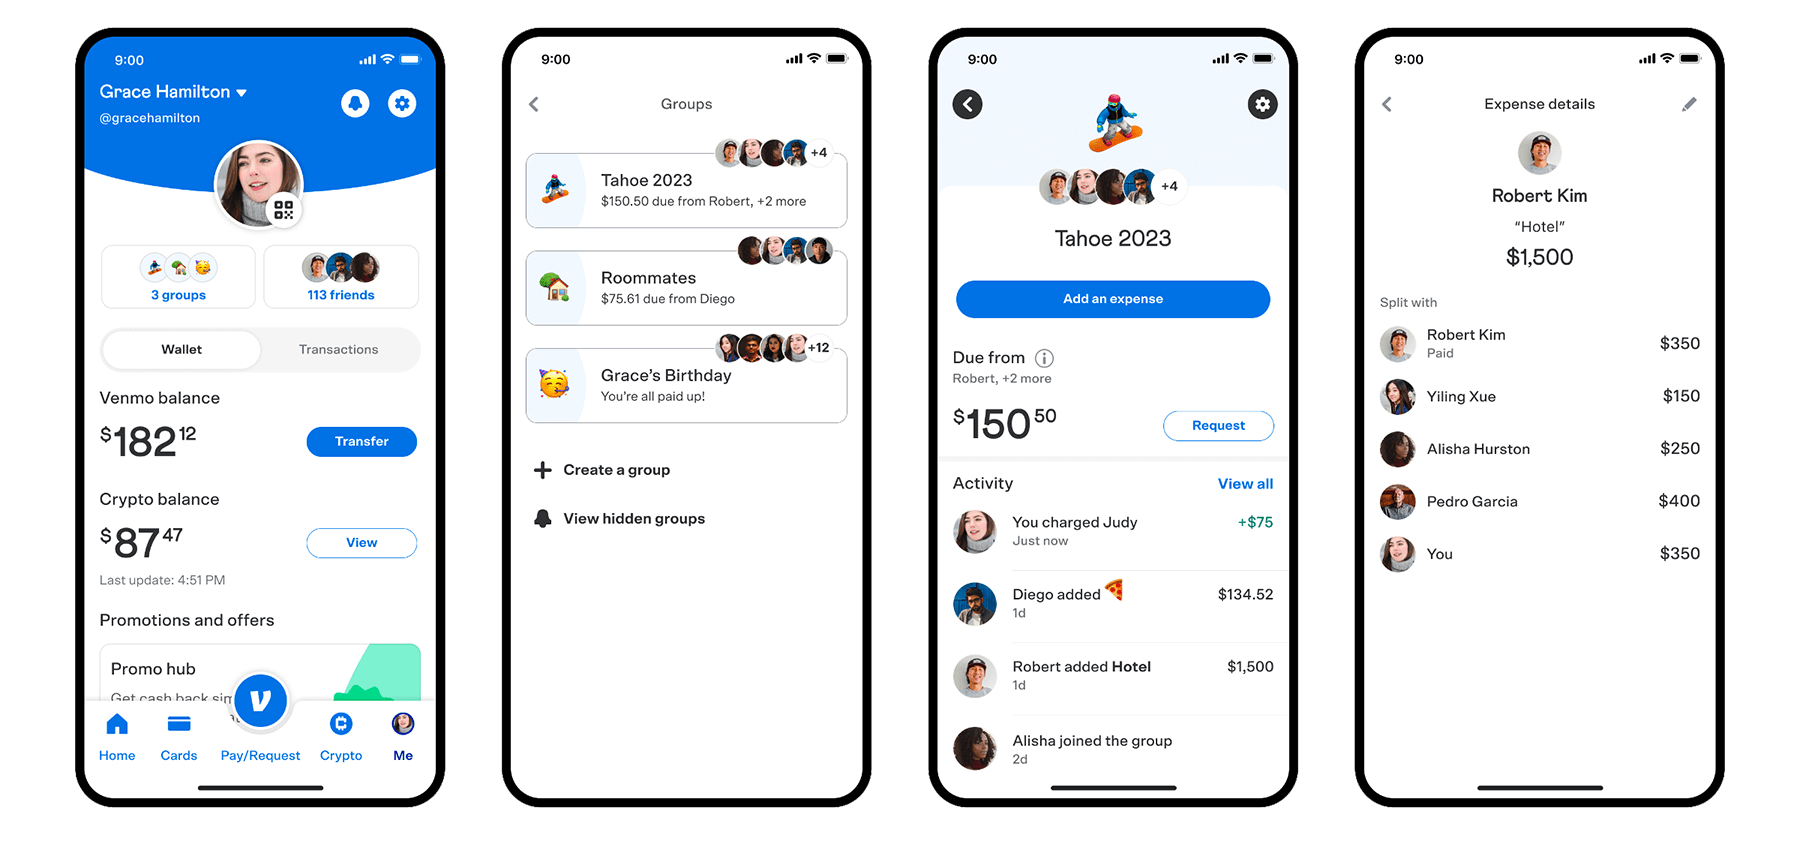
Paypal-owned US payments app, Venmo.
PayPal is increasingly relying on its US-based peer-to-peer payments app Venmo as it seeks to accelerate growth in its traditional branded checkout business. Venmo’s transaction volume grew at a mid-teens rate in the third quarter, while monthly active debit card accounts climbed more than 55% year on year to 6.7 million.
The company is also looking to gain more revenue from its existing customer base by expanding adoption of financial services and strengthening engagement across its payments ecosystem.
Cost reductions remain central to the recovery. PayPal has already reduced its workforce by more than 2,000 positions and removed three management layers across most areas of the business.
The company is targeting more than US$700 million in gross run-rate cost savings exiting the fourth quarter of 2026, as part of a broader goal of at least US$1.5 billion in gross run-rate savings over two to three years. The plan includes workforce reductions, organisational restructuring and greater use of AI and automation.
Competition remains a significant challenge, with Apple Pay, Google Pay and other fintech rivals putting pressure on digital payments providers. PayPal’s ability to restore stronger growth in branded checkout while expanding newer financial services will be a key test of the turnaround.
The improved outlook also comes amid takeover speculation following reports of acquisition interest involving Stripe and Advent International. The reported interest adds another dimension to PayPal’s future. Management, however, emphasises its focus in executing its turnaround strategy.