Smartphone Shipments To Fall 12 Per Cent As Buyers Shift To Premium Devices
 April Ossington
16 Sep 2026
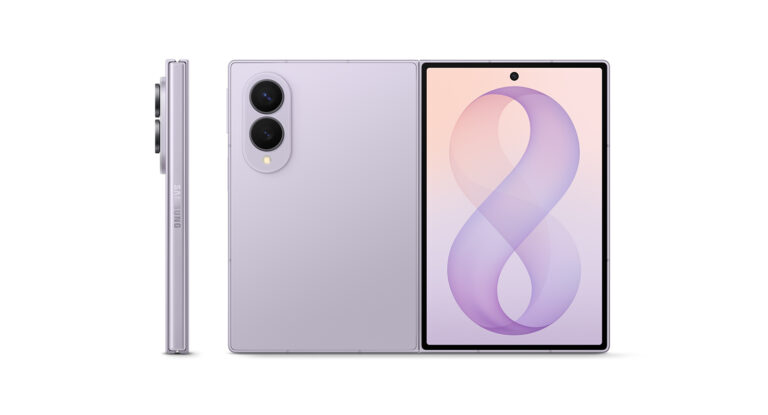
Global smartphone shipments are forecast to fall sharply in 2026 as rising prices, longer replacement cycles and weaker demand for entry-level handsets reshape the market.
Omdia expects worldwide shipments to decline 12 per cent year-on-year to 1.097 billion units this year. Despite fewer phones being sold, the value of the market is forecast to climb 12 per cent to US$651.6 billion (around A$917 billion), driven by consumers and manufacturers moving towards more expensive devices.
Average selling prices are expected to jump 27 per cent to US$594 (around A$836) in 2026.
The shift is particularly noticeable at the cheaper end of the market. Smartphones priced below US$200 (around A$282) represented 40.6 per cent of global shipments in 2025, but Omdia expects that share to fall to 25.6 per cent by 2027.
Ultra-budget phones costing less than US$100 (around A$141) are expected to experience an even steeper decline, falling from 12.6 per cent of shipments in 2025 to just 3 per cent in 2027.
At the other end of the market, phones costing more than US$800 (around A$1,127) are forecast to increase their share from 21.1 per cent to 28.4 per cent over the same period.
By 2027, Omdia expects premium smartphones priced above US$800 to account for a greater proportion of shipments than the entire sub-US$200 category.
Mid-range smartphones priced between US$200 and US$699 (around A$282 to A$985) are expected to remain comparatively stable, accounting for roughly 40 to 41 per cent of shipments.
Omdia senior research manager Jusy Hong said the smartphone price structure was undergoing a significant change as affordable devices lose ground and premium models capture a greater share of sales.
Several factors are contributing to the change, including consumers keeping their phones for longer. Extended software support from major manufacturers has made it easier to hold onto devices for additional years, while improvements in smartphone performance have reduced the need to upgrade frequently.
The growing second-hand and refurbished market is also changing purchasing behaviour. Previous-generation flagship phones can increasingly compete with new entry-level and mid-range devices on price, while trade-in and certified refurbishment programs from manufacturers and carriers are making used premium devices more accessible.
Higher component costs are adding further pressure, particularly in emerging markets where consumer purchasing power has not kept pace with smartphone prices. Omdia expects affordability to remain a major issue across Africa, India, Southeast Asia and Latin America.
Smartphone manufacturers are also placing greater emphasis on profitability rather than chasing shipment volumes. This is encouraging some brands to reduce their reliance on low-margin entry-level devices and concentrate on higher-value products.
At the same time, improvements in mid-range smartphones are narrowing the gap with flagship devices. Features including OLED displays, high refresh rates, improved computational photography, faster charging and stronger processors have become increasingly common outside the premium segment.
Omdia expects these trends to continue beyond 2027, with longer replacement cycles, higher prices and an expanding refurbished market likely to further reshape how consumers buy smartphones.