OZ Personal Audio Market Falls JBL, Beats & Sony Big Winners
 David Richards
04 Jan 2024
Apple’s Beats, Harman’s JBL and Sony personal audio products were the big global winners in 2023 despite sales overall falling 3% in the last quarter according to Canalys ‘research.
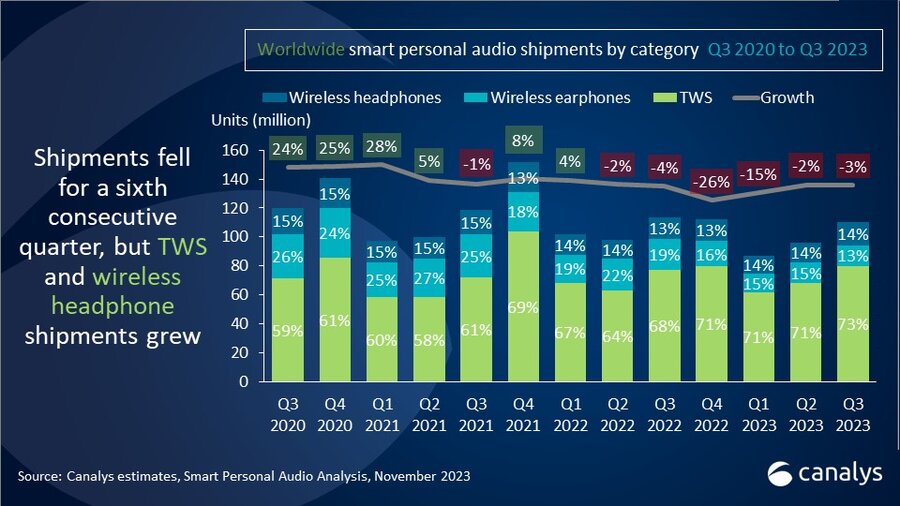
Overall smart personal audio shipments fell 3% year on year to 110 million units in Q3 2023, with markets such as Australia struggling with falls in sales of up to 12%.
True Wireless made up 73% of shipments, as they continue to penetrate affordable mass-market segments.
Retailers are also reporting a surge in demand for over ear headphones as demand for buds’ wanes.
Also in demand is bone conduction headphones and while the market is growing it’s still only 2% segment of the market.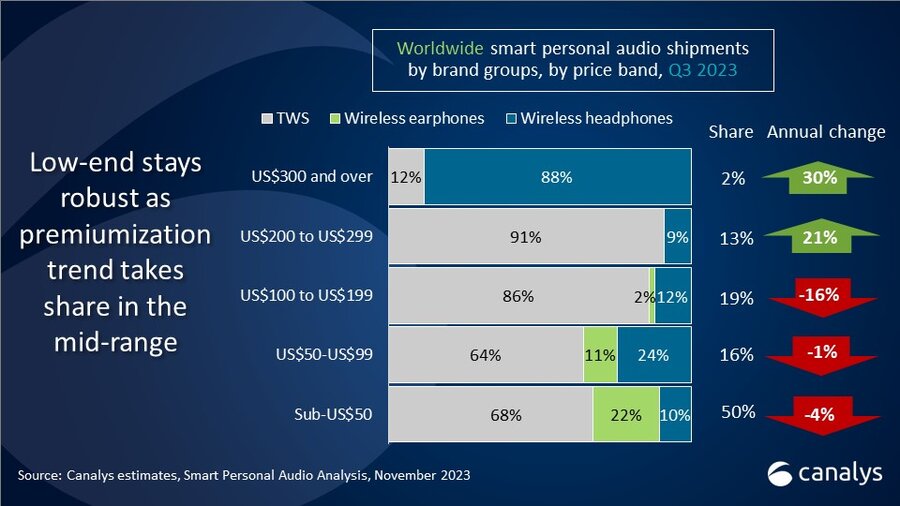
Despite being niche, these devices highlight ongoing form factor innovation in search of profit and differentiation in a saturated market.
In several markets including Australia, the USA and Europe shipments of wireless headphones surpassed those of wireless earphones for the first time, predominantly due to vendors seeking stronger revenue drivers through wireless headphones and wireless earphones being replaced by TWS.
Alternative wearable forms, such as air and bone conduction devices, made up less than 2% of shipments in Q3.
“Demand for smart personal audio devices remains robust despite this quarter’s decline,” said Jack Leathem, Research Analyst at Canalys. “But there were big differences between regions. Australia, the USA, and Western Europe fell 12% reflecting the challenging business environment that is now impacting retailers.
The big plus for Australia is that there is a strong premium segment alongside the entry-level segment that allows more margin to be gained from a sale.
The Q3 decline was partly caused by vendors’ strategic decision to skip yearly flagship releases, effectively extending refresh cycles following vendors prioritising premium models. At the same time, the mid-range segment declined in Q3, lacking clear value-for-money offerings as audio quality and ANC has spread to the low end.”
“We expect growth to return in Q4, driven by replenishing inventories and holiday shopping season deals”, said Leathem. “Looking to 2024, feature-based innovation will help boost shipments. Vendors will prioritize increased device capabilities, such as spatial audio, hearing enhancements and Bluetooth LE, to match product developments from their competitors. Improving economic conditions and expected flagship portfolio launches from Apple and the Samsung owned Harman who also own the JBL brand., should further boost the market in 2024.
Canalys estimates that total shipments for 2024 will be 3.3% higher than in 2023.
But competition in the market will remain fierce across price segments. In this competitive environment, building brand strength and visibility must be a priority for vendors.
Using partnerships, collaborations, special editions, and interactive in-store stands are among the tools vendors should use to tempt consumers away from the status quo.