Australian TV Market Being Dramatically Reshaped
 David Richards
30 Sep 2026
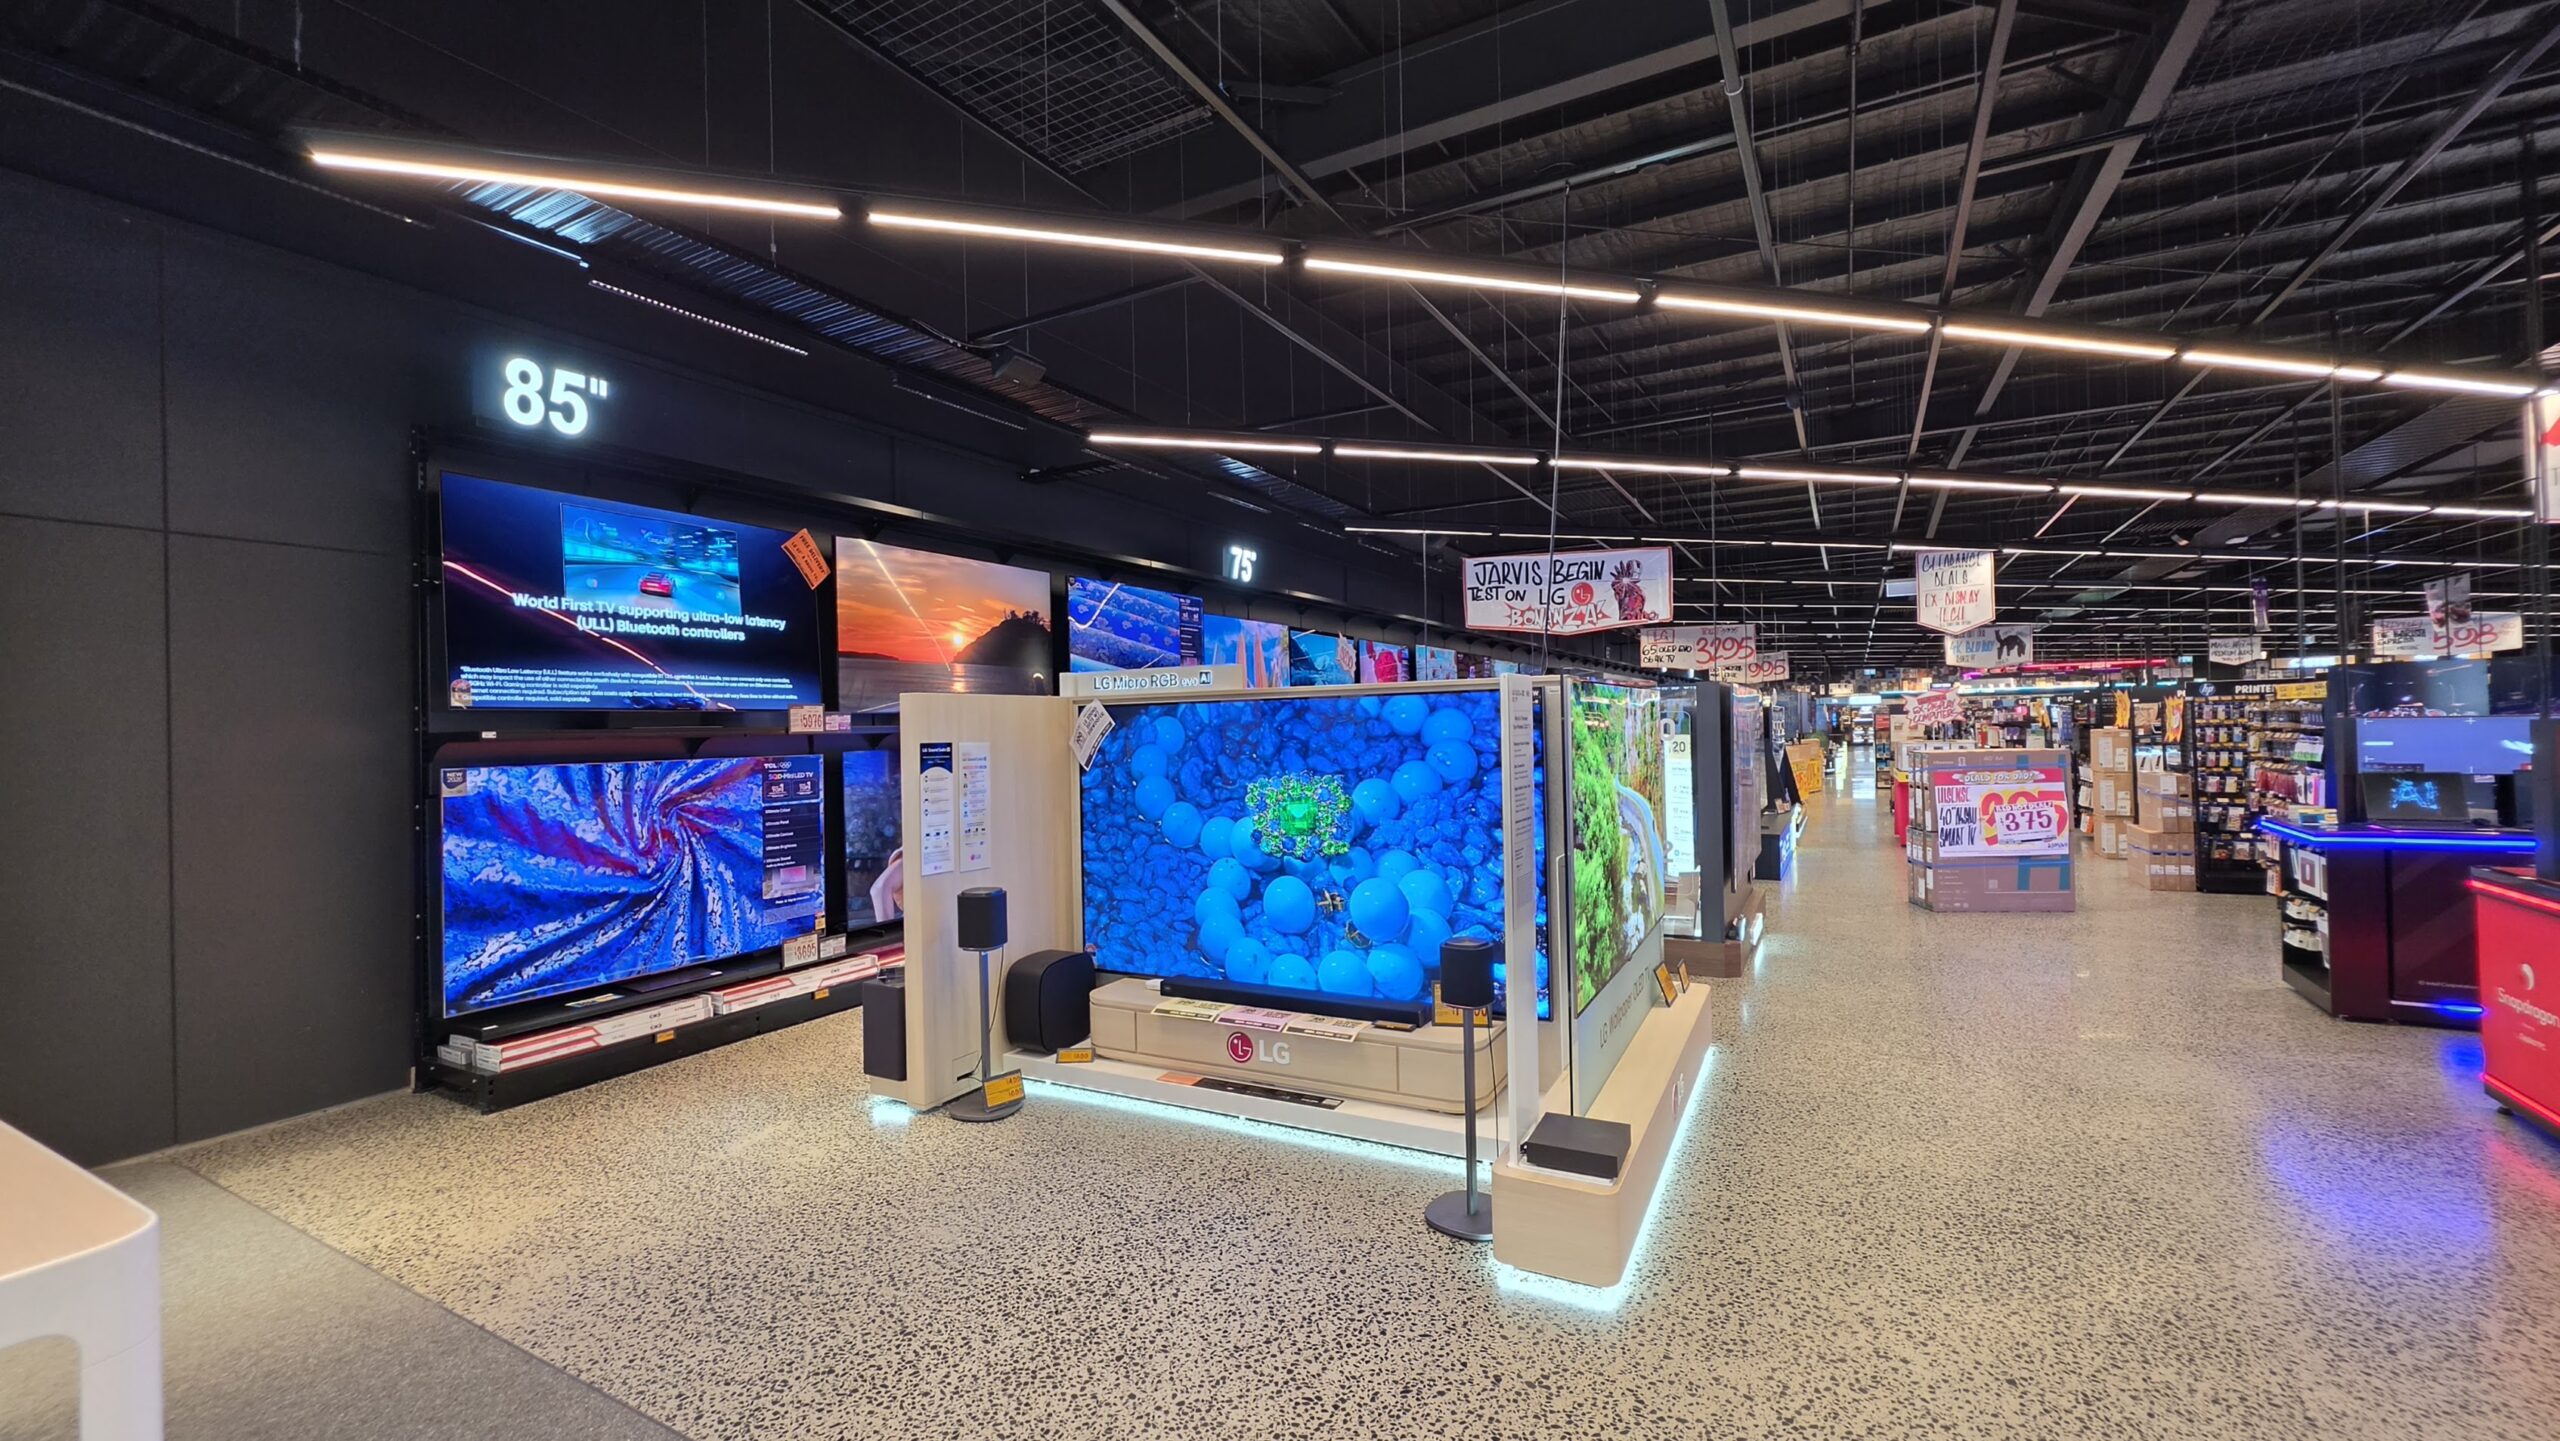
The Australian TV market is being dramatically reshaped as Samsung, TCL and Hisense, three manufacturers that once joined forces to challenge LG Electronics and OLED technology, head in very different directions.
The biggest turnaround has come from Samsung.
After spending years championing QLED as an alternative to OLED, Samsung has rapidly emerged as LG Electronics’ biggest competitor in the OLED TV market, while simultaneously investing in MiniLED and its new Micro RGB technology.
The strategy is already stripping OLED share from LG.
Samsung shipped around 2 million OLED TVs globally in 2025, up 38.1% year on year, giving the company approximately 31% of global OLED TV unit shipments, according to Omdia data.
LG remained number one, shipping approximately 3.22 million OLED TVs and holding 49.7% unit share.
But the gap is closing even faster when measured by revenue.
By the first quarter of 2026, Samsung had captured 40.1% of global OLED TV revenue compared with 46.5% for LG Electronics.
It represents an extraordinary turnaround for Samsung, which only seriously re-entered the OLED TV market in 2022 and had an estimated 0.3% of OLED TV revenue that year.
In less than four years, Samsung has gone from being one of OLED’s biggest critics to capturing 40% of the market by revenue.
Former QLED Allies Split
The shift also marks the effective collapse of a technology alliance that began almost a decade ago.
Samsung, Hisense and TCL were closely aligned in 2017 when they backed QLED as an alternative to LG’s OLED technology.
Initially, the three manufacturers largely sang from the same hymn sheet, moving from QLED towards MiniLED LCD televisions as they sought brighter pictures, better colour and improved contrast without adopting OLED.
That alliance has now fractured.
Samsung is aggressively expanding OLED while simultaneously pushing into RGB LED technology, marketed as Micro RGB, and lower cost MiniLED LCD televisions.
Hisense has placed a significant bet on RGB MiniLED technology as a potential premium alternative to OLED.
TCL, meanwhile, remains firmly committed to quantum dot based MiniLED technology and argues that increasingly sophisticated backlighting, more dimming zones and its latest generation of quantum dot technology can deliver a superior premium LCD television.
LG Electronics remains heavily committed to OLED, the technology that helped establish the company as the dominant premium TV manufacturer for more than a decade.
The result is no longer simply a battle between OLED and QLED.
The world’s biggest TV manufacturers now fundamentally disagree over what technology will dominate the next generation of premium televisions.
Samsung Loses MiniLED Ground
The changing strategies are particularly evident in MiniLED.
In 2022 Samsung accounted for approximately 76% of global MiniLED LCD TV shipments, according to Omdia, compared with 12% for TCL and just 2% for Hisense.
Samsung sold its premium MiniLED LCD televisions under its Neo QLED branding.
By 2024 both Chinese manufacturers had overtaken Samsung in MiniLED shipments, and during 2025 TCL and Hisense extended their lead over the world’s largest TV brand.
The difference is not simply sales volume.
TCL and Hisense have aggressively increased the number of local dimming zones in their premium MiniLED televisions, in many cases offering significantly more zones than comparable Samsung models.
The number and sophistication of dimming zones are important factors in controlling backlighting, improving black levels and reducing blooming around bright objects.
Samsung Changes Direction
During 2026 Samsung again changed its LCD strategy.
The company introduced a new range simply branded “Mini LED”, positioned below its premium Neo QLED products.
Unlike traditional Samsung QLED models, some of the new televisions eliminate the quantum dot sheet and instead use white MiniLED packages, reducing manufacturing costs.
“Samsung plans to replace its mainstream QLED lineup with a new Mini LED series,” Omdia Principal Analyst Jimmy Kim observed.
There is another twist.
Some Samsung televisions are being manufactured by TCL’s panel and manufacturing operations, despite TCL increasingly becoming one of Samsung’s most aggressive competitors.
TCL has also challenged Samsung’s use of MiniLED terminology in the US, arguing that televisions without the technology TCL considers fundamental to a genuine MiniLED implementation should not be marketed in the same way.
The dispute demonstrates how far the relationship between the former QLED allies has deteriorated.
Samsung Now Fighting On Multiple Fronts
Samsung’s strategy, however, should not simply be characterised as abandoning QLED for OLED.
The Korean manufacturer increasingly appears to be technology agnostic.
It is using OLED to attack LG directly in premium televisions while developing Micro RGB for the emerging ultra premium LCD market and expanding MiniLED products into lower price points.
That gives Samsung the ability to compete across several display technologies rather than betting the television business on a single platform.
Its rapidly expanding OLED range is particularly important.
Samsung’s Australian OLED offering has expanded substantially, with multiple S series ranges and screen sizes spanning mainstream premium through to flagship products.
OLED is no longer an experimental category for Samsung.
It has become one of the company’s principal weapons in the premium television market.
The Irony For LG
There is another irony in Samsung’s assault on LG Electronics.
Samsung’s OLED growth can also benefit LG.
LG Display remains the world’s dominant supplier of large OLED television panels and Samsung Electronics has become one of its customers.
Omdia has estimated LG Display’s share of global OLED TV panel supply at more than 80%, with both LG Electronics and Samsung Electronics among its major customers.
This creates an unusual competitive relationship.
LG Electronics can lose the sale of an OLED television to Samsung while another LG business potentially makes money supplying Samsung with the OLED panel used inside the competing television.
Samsung also sources QD OLED panels from Samsung Display, meaning its OLED television strategy is no longer tied to a single panel technology or supplier.
OLED Market Growth Tells Another Story
Samsung’s OLED growth becomes even more significant when viewed against the performance of the broader OLED TV market.
OLED television panel shipments increased only modestly during 2025, according to Omdia, while Samsung’s OLED TV shipments increased 38.1%.
This indicates Samsung is not simply benefiting from a rapidly expanding OLED market.
It is taking share.
LG still leads OLED globally, but its dominance is no longer what it once was.
LG controlled 52.4% of global OLED TV shipments in 2024. That slipped below 50% during 2025, while Samsung continued to expand.
By Q1 2026, the difference between the two companies in OLED TV revenue share had narrowed to only 6.4 percentage points.
TCL And Hisense Bet Against OLED
TCL and Hisense are taking a very different approach.
Rather than following Samsung aggressively into OLED, the two Chinese manufacturers are betting that advances in LCD technology can deliver OLED class performance without some of OLED’s limitations.
Hisense is heavily backing RGB MiniLED, where independently controlled red, green and blue LEDs are used in the backlight instead of relying on conventional white or blue LEDs and colour conversion technologies.
Samsung is also moving into this market with Micro RGB.
TCL has taken another route, continuing to develop MiniLED combined with increasingly advanced quantum dot technology.
The company believes quantum dots, increasingly sophisticated backlight control and dramatically higher numbers of dimming zones can continue pushing LCD picture quality forward.
This means four of the world’s most important television manufacturers are now pursuing distinctly different strategies.
LG is defending its leadership in OLED.
Samsung is attacking LG with OLED while simultaneously hedging its bets with Micro RGB and MiniLED.
Hisense is making RGB MiniLED a major pillar of its premium television strategy.
TCL is betting heavily on the next generation of quantum dot MiniLED.
What began as Samsung, TCL and Hisense collectively challenging LG’s OLED dominance has therefore turned into a four way technology battle.
And after Samsung went from virtually no presence in OLED to around 40% of global OLED TV revenue in less than four years, LG can no longer assume that the market it created and dominated for more than a decade is its own.