OPINION: Serious Questions Raised About Management Practises At Colonial First State As Fines And Payouts Mounts
 David Richards
01 Nov 2026
Colonial First State (CFS), the superannuation giant that has racked up more than $240m in court penalties, class action settlements and member compensation in recent years, has failed to release more than $100,000 that a member asked to move out of his account more than two months ago.
That member is the author of this story.
Two separate sets of transfer forms, a check by an accountant, several phone calls and an unexplained “security” issue later, the money has still not arrived. CFS management has not responded to requests for comment.
The case comes as CFS’s ownership is in limbo, with a planned $5bn sale reportedly collapsing and Commonwealth Bank said to be in talks to buy back the 55% stake it sold to US private equity giant KKR.
Two sets of forms, no transfer.
After moving more than $100,000 from my self managed super fund into a CFS account, I decided several months later to take the money back out.
The first set of transfer forms went nowhere.
No money moved and no explanation was given.
A second set of forms was lodged. Again, nothing.
My accountant then checked the paperwork and confirmed the forms had been correctly completed and filed.
Weeks later, the money is still sitting with CFS.
After several calls I was eventually put through to an online support operator who said there was a “security” issue.
There was no explanation of what the issue was, and no email or written notice had ever been sent alerting me to it.
Days ago I was assured the transfer was under way.
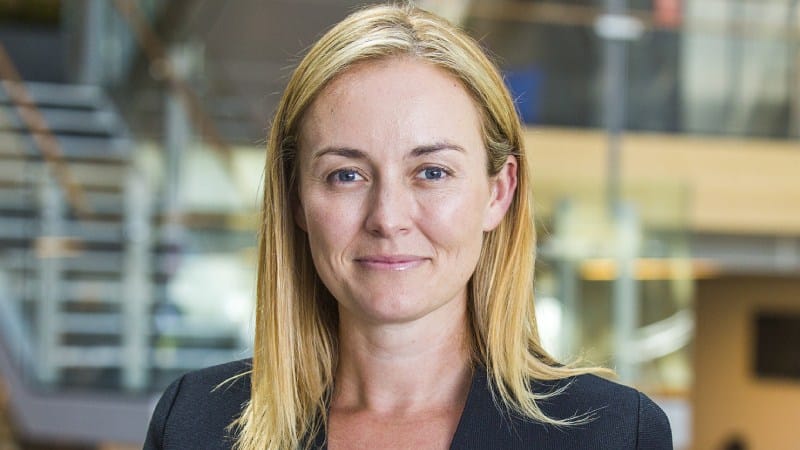
Kelly Power Chief Executive Officer Superannuation- Colonial First State, I doubt that she is concerned about the brand image of the Superanuation Fund or the fact that people cannot get there money out. The Companies actions appear to be deliberate and calculated.
It has still not arrived.
In the meantime the funds remain inside CFS, exposed to fees and market movements I asked to exit two months ago.
CFS’s online systems have not helped.
The website repeatedly crashed during the process, and its “e-post” document system looks and works like something from the DOS era.
Members report the same problems.
I am not alone. On consumer review site ProductReview, CFS rates just 1.6 out of five stars.
One reviewer, Paul T, described an almost identical experience trying to transfer his super to New Zealand.
“Trying to transfer my own super has been unnecessarily difficult with this organisation,” he wrote. “I submitted my Kiwi transfer twice and both times they claimed my certified driver licence was ‘unclear’. It isn’t. It’s clearly visible, legible, and properly certified.”
“Instead of explaining what’s actually wrong, they send vague responses and keep shifting the issue.”
“First it was account details, now it’s ID quality, despite no change in the documents. Every time I address something, a new ‘problem’ appears.”
“This feels less like compliance and more like unnecessary obstruction to delay access to my own money.”
In my case, the shifting problem was a security issue nobody would explain.
Other reviews describe members being hung up on, account details recorded incorrectly, forms that never arrived and website complaints that went unanswered for more than two months.
A record of fines and payouts.
The transfer delays echo the conduct that has already cost CFS heavily.
In 2021 the Federal Court ordered CFS to pay a $20m penalty for misleading members of its FirstChoice superannuation fund.
The court found CFS made misleading representations on at least 12,978 occasions, including telling members that legislative changes required CFS to contact them for an investment direction to stay in FirstChoice. That was not true.
The court found the communications were aimed at keeping members in FirstChoice rather than moving them to a cheaper MySuper product.
By the time of the judgment CFS had paid $67m to remediate 5,815 members, with that figure expected to rise.
In 2022 CFS paid $56.3m to settle a Maurice Blackburn class action on behalf of around 100,000 members.
The case alleged CFS was too slow moving $3.2bn in default balances into lower cost MySuper products, leaving members paying higher fees. Slow movement of members’ money is an allegation that will sound familiar to anyone currently waiting on CFS.
In 2023 CFS agreed to a further $100m settlement of a separate Slater & Gordon class action over grandfathered commissions.
CFS denied the allegations in both class actions and settled without admitting liability.
Ownership in limbo
CBA sold 55% of CFS to KKR in a deal that completed in 2021, valuing the business at $3.3bn. KKR is a New York based global investment firm and one of the world’s largest private equity houses.
A planned $5bn sale of CFS has now reportedly collapsed, with CBA said to be in talks to buy back KKR’s stake.
Regulators
The pattern of complaints raises questions for the three bodies responsible for oversight:
Australian Prudential Regulation Authority (APRA), which regulates super funds’ financial soundness, governance, risk management and compliance with prudential standards.
Australian Securities and Investments Commission (ASIC), which investigates misconduct, misleading representations and failures to act in members’ best interests.
Australian Financial Complaints Authority (AFCA), the independent body that handles disputes between members and super providers, including CFS.
CFS was contacted for comment.
Have you had trouble getting your money out of Colonial First State? Contact ChannelNews at [email protected]