OPINION: David Jones 2.0: Who Pays For Anchorage’s Second Chance?
 David Richards
05 Nov 2026
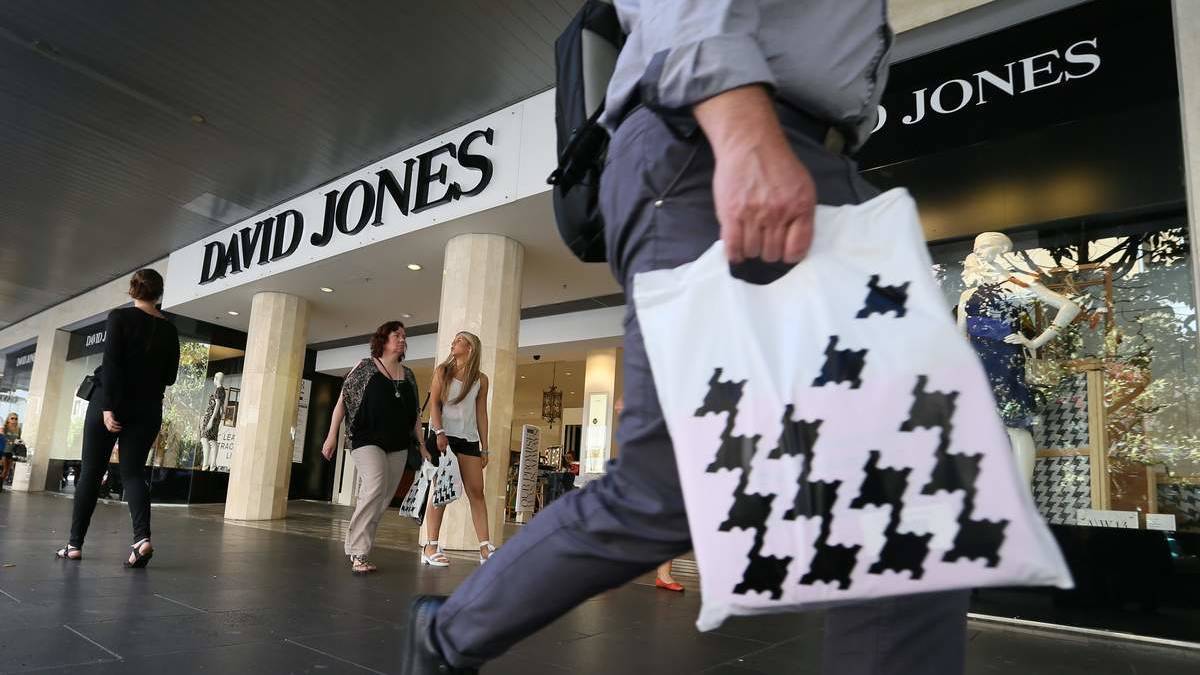
Before anyone starts celebrating a reborn “David Jones 2.0”, there is one question that deserves an answer: who gets left with the bill?
Because if Anchorage Capital Partners emerges owning a leaner retailer after suppliers take losses, landlords make concessions and staff lose their jobs, the applause should wait.
The private equity firm that bought David Jones promising a turnaround should have to explain why it deserves another go—and what everyone else would have to sacrifice to make that possible.
David Jones has entered administration and receivership after negotiations with its major landlord, Westfield operator Scentre Group, broke down. Anchorage’s existing investment is reportedly likely to be wiped out.
That is a significant loss, but it does not settle the question of whether Anchorage could benefit from buying back a restructured business.
Losing money on the first deal and seeing an opportunity in a second are perfectly compatible.
That is why any proposed Anchorage comeback deserves scrutiny, rather than a welcoming committee.
We Have Seen Their Sales Pitch Before
Australians have good reason to examine Anchorage’s retail credentials closely.
Dick Smith remains the obvious starting point.
Anchorage bought the electronics retailer from Woolworths in 2012 for reported consideration of approximately $115 million, including $20 million upfront. The subsequent float valued the business at $520 million. That valuation was not Anchorage’s profit, but the transaction generated substantial returns for the private equity owner.
Anchorage exited before Dick Smith collapsed in January 2016. That distinction matters. So does the difference between a successful investment exit and a retailer built to last.
Investors can celebrate the first while employees and suppliers discover, much later, that they were relying on the second.
Forager Funds famously attacked the Dick Smith transaction in an analysis titled “Dick Smith is the Greatest Private Equity Heist of All Time”, questioning the role of inventory liquidation and acquisition accounting in the turnaround story. That was an investment manager’s assessment, not a court finding of theft or fraud.
But the criticism captures the reputational problem Anchorage now faces: a profitable private equity transaction does not automatically amount to a successful outcome for everyone attached to the business.
A Reset For Whom?
David Jones presents a different situation. This time, the retailer has failed while still under Anchorage ownership.
The firm acquired a troubled business. It did not create every problem David Jones faced. Department stores have struggled with changing shopping habits, online competition and expensive store networks for years.
But those difficulties were hardly a secret when Anchorage bought it.
Identifying distressed businesses and fixing them is the proposition private equity turnaround specialists sell. When the turnaround ends in administration, management cannot reasonably expect the conversation to stop at difficult market conditions.
The question is what their ownership achieved—and what it failed to fix.
Now comes the prospect of a smaller David Jones, relieved of some of the commitments that made the original investment so difficult.
The Australian has raised the possibility that administration could provide a route to restructuring roughly $1 billion in future lease liabilities. Those commitments are not the same as $1 billion in overdue rent. Nor does administration simply make every lease disappear.
Nevertheless, the commercial attraction is obvious.
A retailer with fewer loss-making stores and lower occupancy costs could be a considerably more attractive investment.
The uncomfortable issue is how much of that improvement would come from better retailing, and how much would come from losses absorbed by other people.
Suppliers’ unpaid invoices are someone else’s working capital. Store closures affect people’s livelihoods. Concessions extracted from creditors have a real cost, even when they appear in a presentation as a cleaner balance sheet.
Explain The Westfield Breakdown
Scentre says Anchorage rejected an offer that would have allowed David Jones to continue trading. That is the landlord’s account, and the full commercial terms have not been publicly established. It does not prove Anchorage deliberately rejected a viable rescue to engineer a better deal for itself.
It does, however, demand an explanation.
What was offered? What did Anchorage consider unacceptable? How much additional funding or exposure would accepting the proposal have required?
And how would that outcome compare with the losses creditors could face under an Anchorage-backed restructure?
Those questions go directly to the credibility of any comeback proposal.
“Commercial confidentiality” would be a deeply unsatisfactory response to businesses being asked to accept less than they are owed.
A Second Chance Must Be Earned
There could be a sound commercial case for Anchorage investing again. Familiarity with the business could help. Fresh capital could preserve jobs and keep stores trading.
But previous ownership should confer no entitlement to the next deal.
Any proposal should face a competitive process and clear scrutiny of the price paid, the money committed and the expected returns to creditors.
If the restructuring takes the form of a deed of company arrangement, creditors vote on it. An asset sale follows a different process. Neither should be reduced to a public relations exercise built around saving an iconic name.
The essential questions are straightforward:
How much fresh money would Anchorage contribute, and what would it receive?
Does Anchorage hold claims against David Jones, and how would those be treated?
What would employees, suppliers and landlords recover?
Have competing buyers been given a genuine opportunity?
Why would this plan succeed where Anchorage’s previous strategy failed?
Calling a possible transaction an established “asset grab” gets ahead of the evidence. The terms remain crucial.
But creditors are entitled to insist that the rescue of David Jones does not become an exercise in making Anchorage’s next investment attractive at their expense.
David Jones deserves a viable future. Its staff and suppliers deserve more than a supporting role in somebody else’s recovery story.
If Anchorage wants David Jones 2.0, it should put its money and its terms on the table.
A second chance for private equity should not come with a compulsory donation from everyone else.