Harvey Norman & JB Hi Fi Shares Climb As Investors Punt On Black Friday
 David Richards
17 Nov 2026

Shares in JB Hi-Fi and Harvey Norman have risen ahead of Black Friday, as investors bet the sales event will release spending consumers have held back, while sceptics warn that heavy discounting could erode profits.
JB Hi-Fi shares are up 6.6% over the past month to $76.56. Harvey Norman is trading at $4.50, up 10% over the same period.
Brokers are divided on JB Hi-Fi. Macquarie has a price target of $87, implying 13.6% upside, and JP Morgan has a target of $80. Morgan Stanley has a sell recommendation and a target of $62, 19% below the current price.
The share price gains reflect investor optimism, but they do not show that trading has improved.
$7.2 Billion Spending Forecast
The Australian Retailers Association and Roy Morgan forecast $7.2 billion in spending over 27–30 November, up 5.5% on last year.
Technology and household goods feature prominently in shoppers’ intended purchases, putting both retailers in the frame.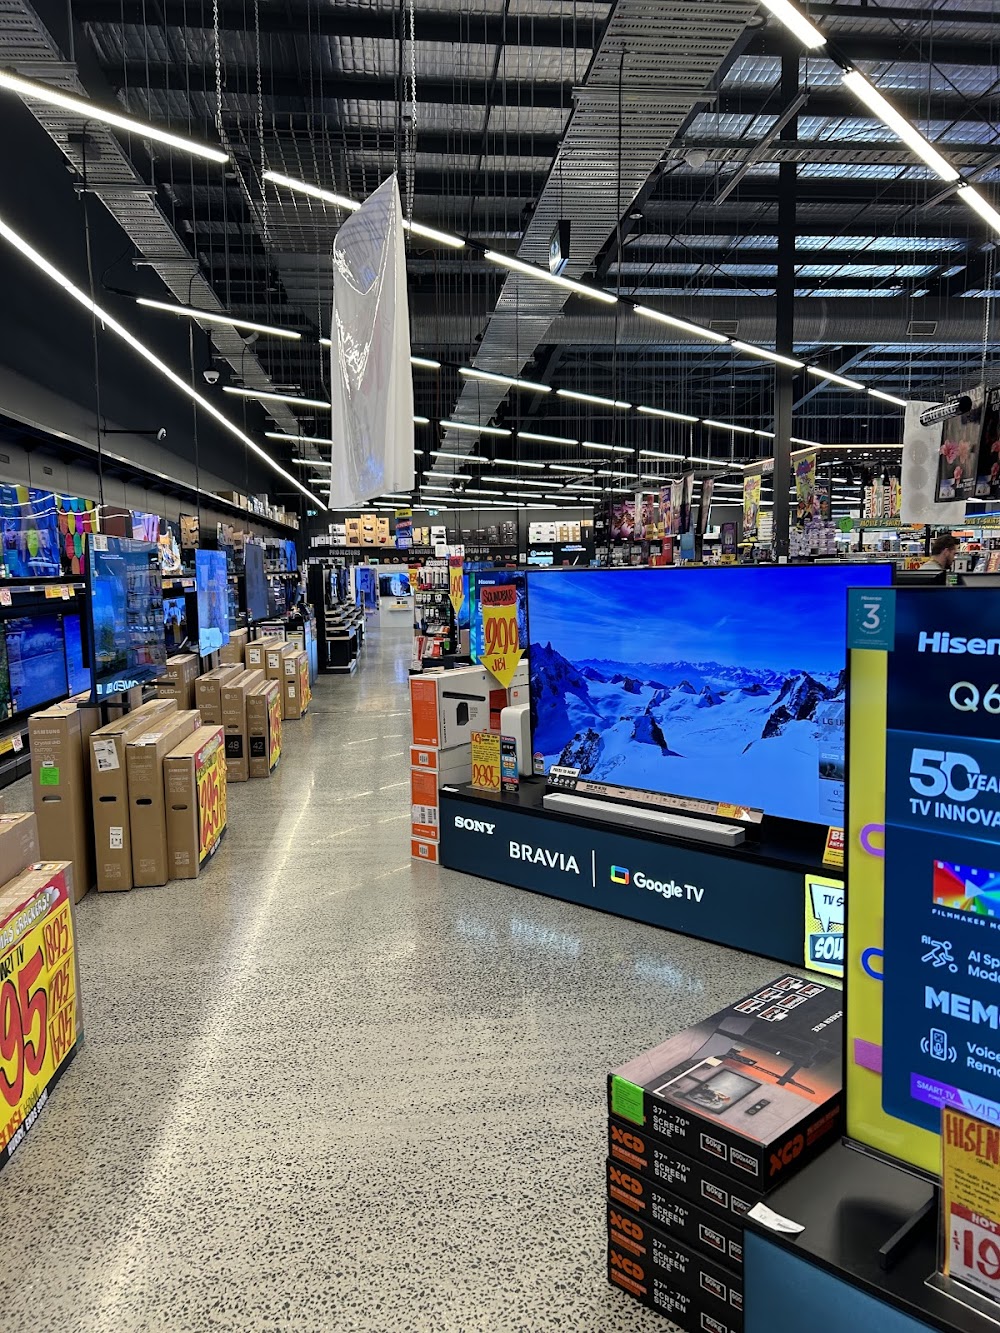
Fewer Australians plan to take part, however, with an estimated 5.8 million shoppers compared with about six million last year. Growth will depend on each shopper spending more.
Macquarie Backs JB Hi-Fi
Macquarie believes JB Hi-Fi’s promotional track record and supplier support could deliver a meaningful lift in sales as shoppers return for deals.
The broker also rates The Good Guys as relatively resilient compared with other housing-related retailers.
Some analysts are telling clients that The Good Guys enters the peak trading period with a modest advantage, based on its demonstrated sales resilience.
Harvey Norman Under Pressure
Harvey Norman faces a more cautious market assessment, with concern focused on housing-related spending and the cost of discounting.
Its FY26 reported pre-tax profit rose 4.9% to $790.29 million, but second-half reported pre-tax profit fell 8.2%. On the company’s adjusted measure, second-half pre-tax profit grew just 0.7%.
Critics argue the stronger full-year result disguises weakening momentum.
Retail researcher Retail Mosaic issued a particularly cautious assessment in September, pointing to slowing sales, falling second-half franchise earnings and the risk that extra financial support for franchisee discounting would hurt profitability. It argues Harvey Norman’s earnings are especially sensitive to a housing slowdown. This is the researcher’s view, not company guidance.
Harvey Norman’s wider category range gives it more ways to capture spending, but furniture and bedding also expose it to purchases households can put off.
Push Into Premium
Suppliers who spoke to ChannelNews say that since Hayden Myers was appointed Executive General Manager Electrical, Harvey Norman has been targeting premium and affordable premium customers.
One franchisee said the retailer was chasing margin and a “better ASP”.
Margins The Real Test
A UBS source said the critical measure for both retailers will be the profit earned from the sales surge, not turnover.
Other analysts warn that strong November sales could still disappoint investors if deep discounts erode margins or simply pull purchases forward from December.
Harvey Norman’s annual general meeting on 25 November, two days before Black Friday, is the next scheduled opportunity for management to update the market on trading. A fresh sales update would allow a firmer comparison with JB Hi-Fi and The Good Guys.