Global Tablet Shipments Plunge 23 Per Cent As Supply Shortages Hit Market
 April Ossington
17 Nov 2026

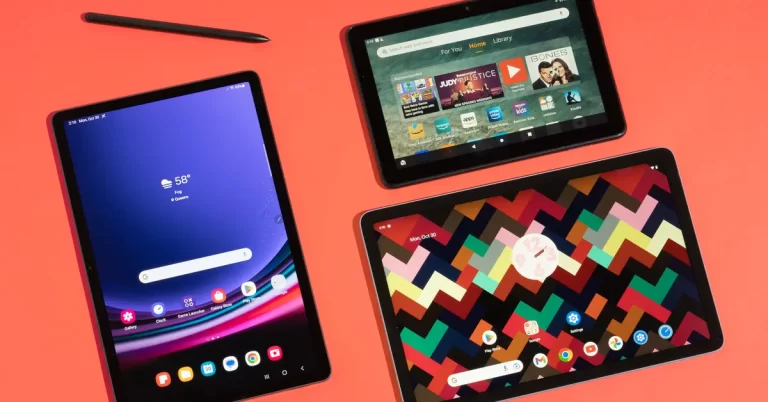
The global tablet market has recorded its weakest quarterly performance in almost three years, with shipments falling 23 per cent year-on-year during the third quarter of 2026, according to new research from Omdia.
Worldwide shipments declined to 32 million units, continuing a downturn that saw the market contract by 10 per cent in the previous quarter. Component shortages and changing manufacturer priorities are placing increasing pressure on the sector, with a significant recovery now considered unlikely before 2028.
The Middle East, China and Western Europe experienced the largest regional declines, highlighting the widespread impact of supply constraints and subdued consumer demand.
Omdia Research Manager Himani Mukka said manufacturers were increasingly directing resources away from tablets as component availability became more challenging.
With supply conditions expected to deteriorate further in 2027, manufacturers face difficulties maintaining production volumes and delivering meaningful upgrades to existing product ranges.
Apple maintained its position as the world’s largest tablet manufacturer, despite shipments declining 28 per cent compared with the same period last year. Its global market share fell to 36 per cent, down from 38.2 per cent in the third quarter of 2025.
Samsung retained second place, shipping 5.4 million tablets during the quarter. This represented a 22 per cent annual decline, leaving the South Korean manufacturer with a 16.9 per cent share of the global market.
Despite introducing new products, Samsung was unable to offset the impact of component shortages, which continued to restrict production and limit growth opportunities.
Lenovo emerged as the strongest performer among the five leading manufacturers, recording a 12 per cent increase in shipments to 4.1 million units.
The company’s market share climbed to 12.7 per cent from 8.7 per cent a year earlier, supported by stronger demand for conventional slate-style tablets. This growth helped compensate for weaker sales of detachable models.
Xiaomi secured fourth position with shipments of 2.3 million units, representing an 11 per cent annual decline. Its global market share stood at 7.3 per cent, although the company benefited from improved performance in Latin America.
Huawei experienced the steepest decline among the five largest manufacturers, with shipments dropping 43 per cent to 1.8 million units.
Despite the overall contraction, Huawei achieved growth in Central and Eastern Europe and the Asia-Pacific region, demonstrating that some markets continued to offer opportunities.
The downturn comes despite a series of major tablet releases during the second half of 2026.
Samsung introduced its flagship Galaxy Tab S12 series, while Apple expanded its range with an OLED-equipped iPad mini. Xiaomi also launched its Pad 9 series, alongside new devices from Huawei, HONOR, OnePlus and realme.
However, the arrival of these products has done little to reverse declining shipment volumes.
According to Omdia, component shortages are restricting manufacturers’ ability to introduce substantial hardware improvements, reducing the differences between new tablets and their predecessors.
This presents an additional challenge for manufacturers attempting to encourage consumers to replace existing devices, particularly when newer models offer relatively modest improvements in performance or functionality.
The situation may also influence purchasing decisions among Australian consumers, although Omdia’s figures do not provide a specific breakdown of Australian tablet shipments.
For local retailers, the broader downturn highlights the potential challenges of maintaining consumer interest in a product category where replacement cycles can be lengthy and significant hardware improvements are becoming more difficult to deliver.
While Lenovo’s performance demonstrates that individual manufacturers can still achieve growth, the overall outlook remains subdued.
Omdia expects supply pressures to continue throughout 2027, with a meaningful recovery in global tablet shipments unlikely until 2028.
For manufacturers, the challenge will be balancing production constraints with the need to deliver compelling new products capable of encouraging consumers to upgrade.