Global Smartphone Shipments Plunge 20 Per Cent To Lowest Third-Quarter Level Since 2013
 April Ossington
30 Oct 2026
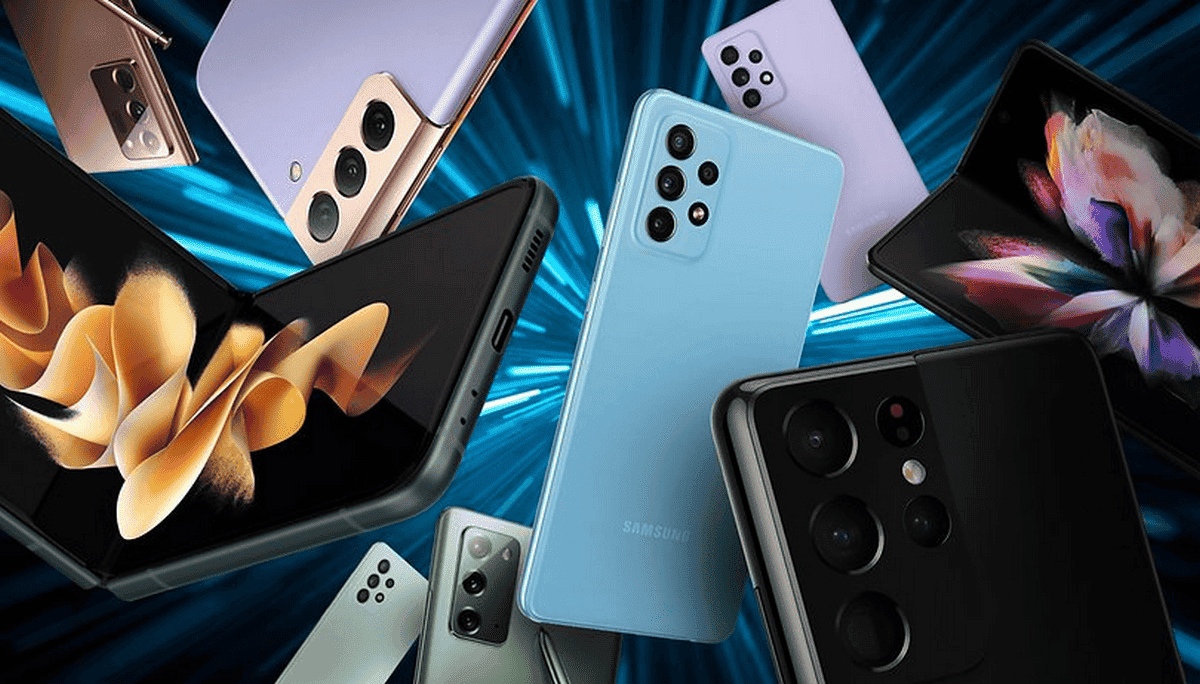
Global smartphone shipments fell sharply in the third quarter of 2026 as rising device prices, component shortages and weaker consumer spending weighed on demand across major markets.
According to Omdia, worldwide smartphone shipments dropped 20 per cent year-on-year to 254.7 million units during the quarter, marking the weakest third-quarter result since 2013.
The decline was particularly severe across emerging markets, where higher smartphone prices, inflation and currency depreciation have reduced consumer purchasing power. Retailers and distributors have also become more cautious about replenishing inventory as rising device costs increase working capital requirements.
Samsung retained its position as the world’s largest smartphone manufacturer, shipping 57.8 million units during the quarter. That represented a decline of 5 per cent compared with the same period last year.
Omdia said Samsung’s Galaxy A range helped the company maintain its market leadership as competing Android manufacturers faced memory supply constraints and higher component prices. The August launch of the Galaxy Z8 series also supported Samsung’s premium smartphone position, helped by trade-in and upgrade programs.
Apple remained in second place with 56.5 million iPhones shipped, unchanged from a year earlier despite the broader market decline.
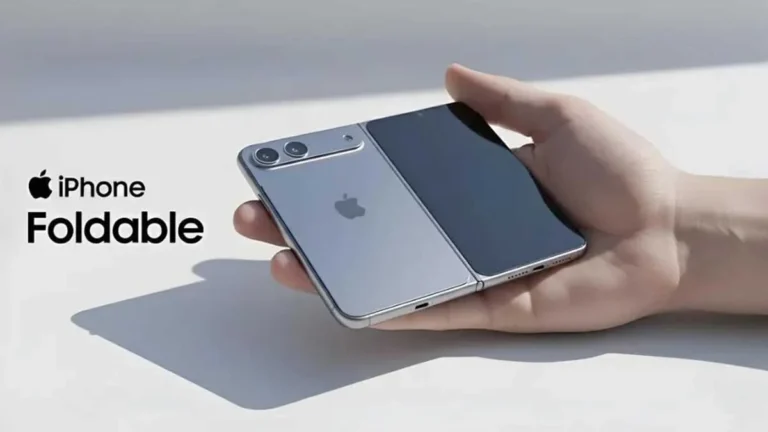
Demand in China and North America helped offset weaker performance across emerging markets, while continued iPhone 17 sales and early channel stocking ahead of expected price increases also supported shipments.
Apple introduced the iPhone 18 Pro, iPhone 18 Pro Max and its first foldable smartphone, the iPhone Duo, in September. The standard iPhone 18 has been pushed into 2027, extending the sales cycle of the iPhone 17 while directing new-product demand towards higher-priced devices.
Xiaomi remained the world’s third-largest smartphone vendor with shipments of 30.7 million units, down 29 per cent year-on-year.
The company recorded shipment declines of 20 per cent in China and 28 per cent in India. Omdia said Xiaomi has been increasing prices in response to higher component costs while prioritising margins over shipment volumes, particularly in price-sensitive markets.
The Redmi A7 Pro and Redmi 17 provided some support, although they were unable to offset the broader decline.
OPPO, including realme and OnePlus, ranked fourth with 23.4 million units shipped, a decline of 39 per cent. Vivo followed with 19.3 million units, down 33 per cent.
Both companies have increased smartphone prices across key markets as component costs rise, making inventory planning more difficult for retailers and distributors.
Omdia said emerging markets are experiencing the greatest pressure.
Africa recorded the steepest regional contraction, with shipments falling 39 per cent year-on-year. Asia-Pacific excluding Greater China, the Middle East and Latin America each recorded declines of more than 20 per cent.
Higher living costs and weaker currencies are also causing some consumers to delay upgrading their phones, move to refurbished devices or, in lower-income markets, switch back to feature phones.
North America has proved more resilient due to its heavier concentration of premium smartphones and wider availability of carrier financing, trade-in programs and device upgrade plans.
Omdia said manufacturers are responding by concentrating on more profitable markets and reducing the complexity of their smartphone portfolios.
Brands are adjusting RAM and storage configurations, cutting the number of individual models offered and selectively absorbing higher costs while expanding premium products in an effort to protect margins.
The industry is also facing continuing pressure from component supply shortages.
Omdia expects worldwide smartphone shipments to decline by 12 per cent across 2026, with additional price increases and fewer opportunities for aggressive discounting expected to affect demand during the holiday period.
Inventory risk is also becoming a growing problem as manufacturers and retailers attempt to balance existing stock against incoming generations of devices.
Large telecommunications operators and major retailers are considered better positioned to absorb higher device costs and working capital requirements. Independent retailers could face greater pressure as slower stock turnover and shrinking margins affect profitability.
Omdia expects the smartphone market to decline again in 2027, although at a slower rate.
Persistent shortages of high-bandwidth memory and constraints affecting conventional memory products are expected to keep component prices elevated.
Manufacturers are expected to respond by cutting sales, retail and marketing expenses while looking for additional revenue from software, subscriptions, services and other post-sale products.
For smartphone manufacturers and retailers, Omdia believes strong balance sheets, tighter inventory management and greater operational efficiency will become increasingly important as the industry adjusts to weaker volumes and higher costs.