Hilco Bankrolls $40M David Jones Black Friday Grab As Westfield Holds The Keys
 David Richards
17 Nov 2026
David Jones’ lender Hilco has lined up another $40 million to restock the collapsed department store ahead of Black Friday. Suppliers already owed more than $100 million are being asked to ship fresh stock, while Westfield owner Scentre quietly decides which stores survive.
Hilco is putting fresh money into David Jones to cash in on the bargain-hunting frenzy sparked by the chain’s collapse. Suppliers are being approached to deliver new inventory, and brands have been told the financier has set aside $40 million in funding.
The aim is to have stores fully stocked before the official Black Friday sales date on 27 November. Hilco and David Jones management are moving to capitalise on a buying spree that took off as soon as the store network went into administration.
Insiders claim the UK-based financier sees minimal risk in the extra capital, and with good reason. Hilco is already in the box seat. David Jones has reportedly drawn down $140 million of its $225 million Hilco facility, which is secured against inventory. Meanwhile suppliers are owed more than $100 million.
ChannelNews recently revealed that the rush of shoppers chasing David Jones bargains was being seen as a way for owner Anchorage Capital to make money from the administration.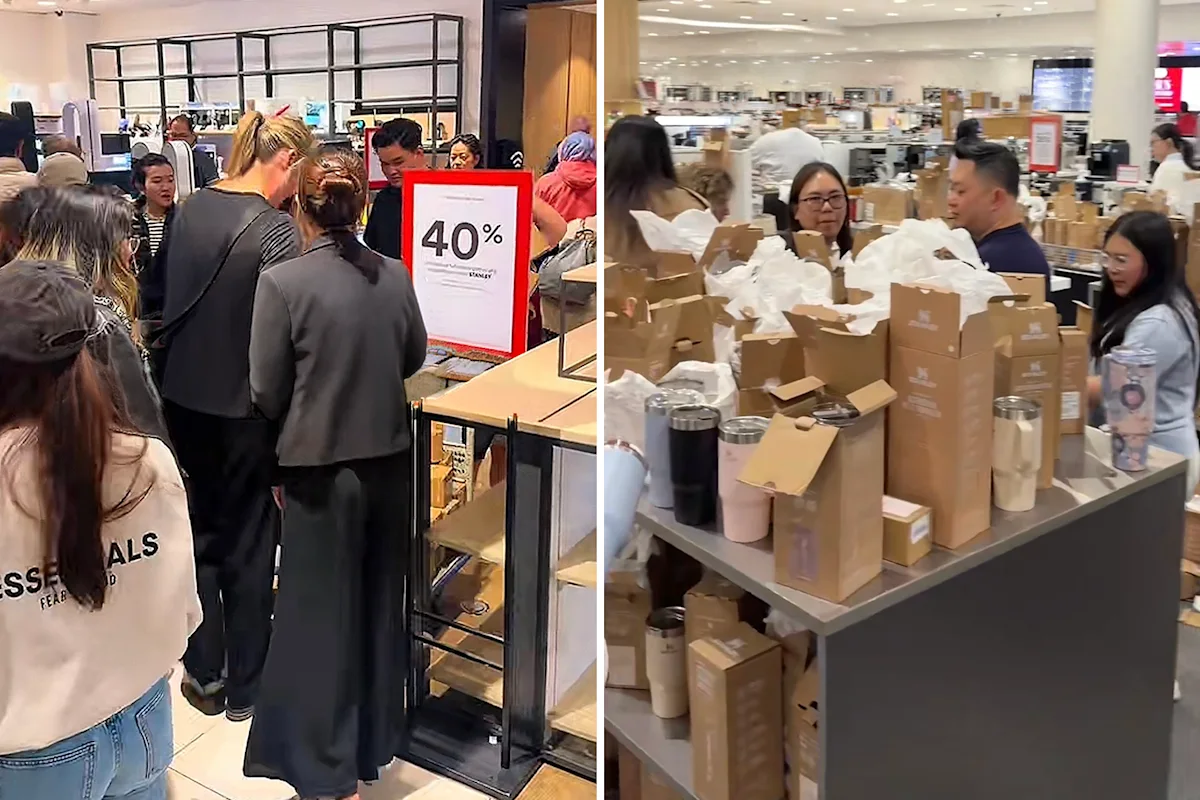
Hilco On The Shop Floor
Hilco is not just funding the stock. It is watching it closely.
One supplier told the AFR that Hilco staff had been placed on the floor in David Jones stores. The supplier said they had a “heavy presence” and were “very involved” in managing their stock.
Questions Over The Administrators
Voluntary administrator McGrathNicol has yet to decide whether to appoint a committee of inspection.
This would be a small group of creditor representatives who would work with, and keep watch over, the administrators.
The decision matters because McGrathNicol is seen in the market as close to Anchorage Capital. The firm worked with the owner before the entire David Jones network was placed into administration.
Westfield Holds The Keys
Scentre Group, which owns Westfield, has the biggest say over where David Jones goes from here.
The chain occupies about 200,000sqm across 17 Westfield centres. Before the collapse it paid Scentre about $45 million a year, or roughly $352/sqm. That is barely 37% of Scentre’s portfolio average of $942/sqm. Put another way, David Jones paid about a third of what a typical Westfield tenant pays.
The deal is believed to have angered several of Scentre’s key tenants, who pay full rates while one of the biggest names in the centre pays a fraction of them.
On an annualised basis, David Jones accounts for about 1.8% of Scentre’s gross rent and about 3.6% of its funds from operations.
Reports indicate David Jones paid rent up to 30 September and then stopped.
“They have not paid rent since September and therefore are in breach,” Scentre CEO Elliott Rusanow said recently.
Scentre saw trouble coming. When Anchorage bought David Jones in 2023, the landlord demanded bank guarantees as a condition of approving the deal. Scentre’s share is $30 million, or about eight months of gross rent.
Scentre also reportedly refused to let the new private equity owners take over as the counterparty on the leases. According to the AFR, most David Jones stores had 10 to 15 years left to run on their leases.
What It Means For Any Buyer
Receiver FTI Consulting, appointed by Hilco, will close 19 of the chain’s 38 stores by the end of the year. 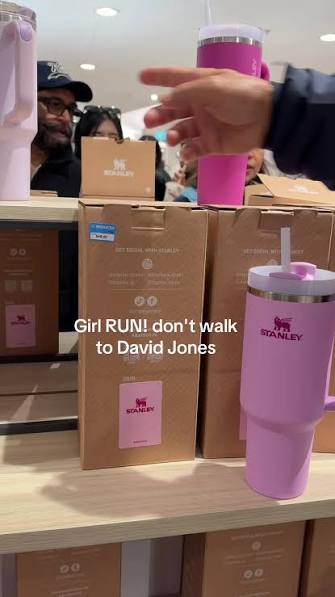
Any buyer, or a “David Jones 2.0”, that wants to keep Westfield sites will need Scentre’s agreement. In the meantime the administrators remain liable for rent on every store they keep open.
The bottom line is that Scentre effectively decides which Westfield stores stay open and on what terms. Any rescue has to go through it.
Scentre’s power has limits. It cannot save David Jones, and it cannot block a CBD-led David Jones 2.0. Its bigger opportunity may be to take back $352/sqm space and re-let it to tenants paying far higher rents.
Sale Timeline Set To Blow Out
ChannelNews understands the administrators will ask for more time to pursue a sale or recapitalisation. That could push the critical second creditors’ meeting back by three months, with lease negotiations set to drag well into 2027.